

In the summer of 1974, Henry Kissinger quietly completed one of the most consequential deals in modern financial history.
The United States had a problem. Two years earlier, Richard Nixon had closed the gold window — severing the dollar’s last link to a physical commodity. The dollar was now backed by nothing except confidence in the US government. Confidence, as any investor knows, is a fragile foundation.
Then came the 1973 oil embargo. OPEC cut supply. Prices quadrupled. The US economy slipped into stagflation. And the dollar’s new role as the world’s reserve currency — unanchored from gold, untested under pressure — was suddenly in question.
Kissinger had a solution. In a series of negotiations conducted largely out of public view, the United States reached an understanding with Saudi Arabia: the Kingdom would price its oil exclusively in US dollars. In return, America would provide military protection to the Saudi regime and guarantee access to US Treasury markets for Saudi petrodollar surpluses.
It was not a formal treaty. It was never ratified by Congress. And it left almost no paper trail.
And, by design, it anchored the global financial order for the next fifty years.
How the Petrodollar Actually Works
If you understand anything from this, understanding how the petrodollar works is critical. Because it has underpinned US Financial Hegemony for 50 + years. The contention of this piece is that the United States is in the process of trying to replicate this for the next 50. It’s literally one of the most important things happening right now.
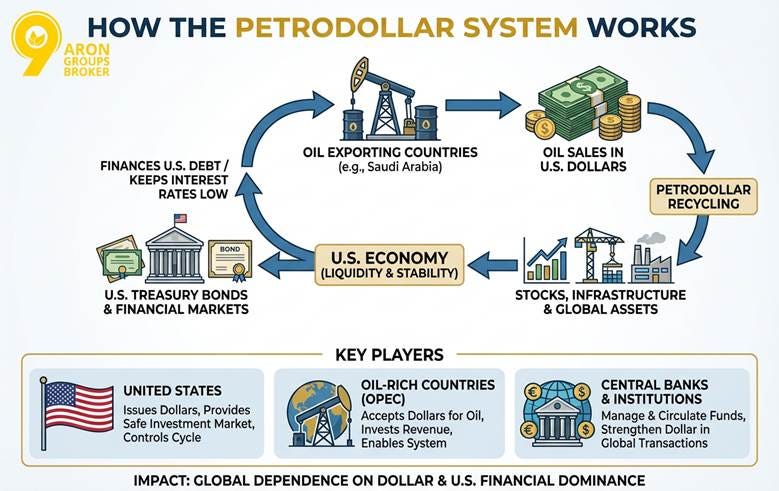
Every nation on earth needs oil to run its economy. Transportation, manufacturing, agriculture, heating — oil is not optional. And after 1974, oil was priced and settled in US dollars. Not yen. Not deutschmarks. Not rubles. Dollars.
This created something extraordinary: forced, automatic, global demand for the US dollar — demand that had nothing to do with whether the world trusted American fiscal policy, liked American foreign policy, or believed in American institutions.
A Japanese car manufacturer buying Saudi crude had to hold dollars. A Brazilian refinery purchasing Nigerian oil had to hold dollars. A German industrial company hedging its energy costs had to hold dollars. The purchase was denominated in dollars, the settlement was in dollars, and the insurance and shipping contracts were in dollars.
The second half of the mechanism was equally important. Oil exporters — Saudi Arabia, the UAE, Kuwait, others — accumulated enormous dollar surpluses from selling oil to the world. Those surpluses had to go somewhere. Kissinger’s deal ensured they flowed into US Treasury bonds.
This “petrodollar recycling” had a profound effect on American borrowing costs. Foreign central banks and sovereign wealth funds became captive buyers of US government debt — primarily because the structure of global oil trade gave them dollars that had to be invested somewhere, and Treasuries were the deepest and safest market available.
The result: the United States could run persistent fiscal deficits, print money to fund them, and export the resulting inflation to the rest of the world — because global dollar demand absorbed the excess. This is what French President Valéry Giscard d’Estaing memorably called America’s “exorbitant privilege.” He meant it as a criticism. He was also simply describing reality.
For fifty years, that arrangement held. And almost nobody outside of finance and geopolitics circles understood it was happening.
I wrote a long-form post on this if you want to go deeper.

But then …
In June 2024, with almost no fanfare, the 50-year petrodollar agreement between the United States and Saudi Arabia lapsed.
Saudi Arabia declined to renew it.
Saudi Arabia did not immediately begin pricing oil in yuan or rubles. The dollar remains, for now, the dominant currency in global oil trade. But the automatic, obligatory nature of the arrangement — the structural compulsion that made it so powerful — is gone.
And the Saudis have been making their intentions clear through their actions:
Saudi Arabia applied for BRICS membership and was accepted. The Kingdom has been exploring petroyuan arrangements with China — Beijing is now Saudi Arabia’s largest oil customer, and the two countries have conducted bilateral trade discussions in renminbi. Gulf states have been examining the mBridge payment network, a cross-border settlement system developed by China, Hong Kong, Thailand, and the UAE specifically designed to bypass dollar-denominated correspondent banking.
Simultaneously, global central banks have been buying gold at the fastest pace in decades. In 2022 and 2023, central bank gold purchases hit records not seen since the 1960s. This is not coincidence. Central banks buy gold when they want reserves that are not denominated in any nation’s currency — when they want an asset that cannot be frozen, sanctioned, or devalued by a foreign government’s monetary policy decisions.
The petrodollar is not dead. But the foundation is cracking.
And if you can understand the profound impact of the system, it really brings to better light a lot of US foreign intervention. And how critically important it is for the United States to build a framework for the future.
The Architecture Being Built
Here is the thesis I want you to sit with, because it is the most important macro story of the next decade — and it is almost entirely absent from mainstream financial commentary:
The United States government is deliberately constructing a new architecture to recreate structural dollar demand for the digital age. The building blocks are semiconductor export controls, AI infrastructure investment, and stablecoin legislation. And the intended mechanism is a near-perfect replica of the petrodollar loop — with compute replacing oil as the indispensable commodity.
I came across parts of this thesis and concept through reading Nicolas Colin, Head of Research at Vsquared Ventures. You can check them out on Substack here.
I’ve also added their substack, Currencies of Power, to my recommended list. Make sure to check them out.
Beyond this point, we dig into what the future of US Financial Hegemony could be built upon, and why it matters for investors of all stripes.
